Splitting bills 50/50 sounds fair until one partner earns $95,000 and the other earns $55,000. Then the lower earner can end up with well under half the spare cash the higher earner has, even though they share the same home.
Most couples in that spot switch to a proportional split. Each person pays the same percentage of their income toward shared bills. It is the simplest fix, but not the only one.
We ran one couple through four common methods. The numbers show exactly who keeps what, so you can pick the one that feels fair in your home.
Split Household Expenses: The Example Couple
Alex earns $95,000 a year. Sam earns $55,000. After tax and retirement savings, Alex takes home about $5,950 a month and Sam about $3,750.
Their shared costs come to $4,800 a month.
| Shared expense | Monthly cost |
|---|---|
| Rent | $2,600 |
| Utilities and internet | $310 |
| Groceries and household items | $900 |
| Car payment, gas and insurance | $620 |
| Phone plan and streaming | $170 |
| Joint savings for trips and repairs | $200 |
| Total | $4,800 |
Four Ways to Split Household Expenses Compared
| Method | Alex pays | Sam pays | Alex keeps | Sam keeps |
|---|---|---|---|---|
| 50/50 split | $2,400 | $2,400 | $3,550 | $1,350 |
| Proportional to take-home pay (61% / 39%) | $2,944 | $1,856 | $3,006 | $1,894 |
| Proportional to gross pay (63% / 37%) | $3,040 | $1,760 | $2,910 | $1,990 |
| Equal leftover | $3,500 | $1,300 | $2,450 | $2,450 |
| Fully pooled | All income goes into one pot | — | Shared | Shared |
Look at the “keeps” columns. Under 50/50, Alex has $2,200 more spare cash than Sam every month. Under a proportional split, the gap shrinks to about $1,100. Under equal leftover, it disappears.
How a 50/50 Split Works
Each partner pays half of every shared bill.
When it works: Incomes are close, within about 10% to 20% of each other, or both partners prefer full financial independence.
Where it breaks: In our example, Sam spends 64% of take-home pay on shared bills. Alex spends 40%. Sam may start to say no to dinners, trips or savings goals that Alex takes for granted. Small resentments often start here.
How to Split Expenses Proportionally to Income
Each partner pays the same share of their income. This is the most common fix for unequal earners.
The formula: Your share = your take-home pay ÷ combined take-home pay.
- Add both take-home incomes: $5,950 + $3,750 = $9,700.
- Divide each income by the total: Alex 61.3%, Sam 38.7%.
- Multiply the shared total by each share: Alex $2,944, Sam $1,856.
Both now spend about 49.5% of take-home pay on shared costs. That feels fair to most couples because the burden is equal, even if the dollars are not.
Gross or take-home? Take-home is fairer when one partner pays a higher tax rate, which is common with bigger incomes. It also counts retirement contributions, which matter to both of you. Gross pay is simpler because it never changes month to month.
How the Equal Leftover Method Works
This method asks a different question: how much should each of us have left for personal spending?
- Subtract shared costs from combined take-home pay: $9,700 − $4,800 = $4,900.
- Split what is left in half: $2,450 each.
- Each partner pays enough to leave exactly $2,450: Alex pays $3,500, Sam pays $1,300.
It treats the household as one team with two equal allowances. Couples who are married, raising children or planning to merge finances later often like it.
The catch: The higher earner carries 73% of the bills. Some higher earners feel that removes any reward for their extra work, so talk it through first.
When Pooling All Income Makes Sense
Some couples put both paychecks into one joint account and pay everything from it. Each person then gets the same personal allowance, say $500 a month, with no questions asked.
It works well when:
- You are married or fully committed and share long-term goals.
- One partner is at home with children or between jobs.
- You both find tracking separate payments stressful.
Fully pooled finances need trust and a shared budget. They also mean both names on one account, so plan for what happens if the relationship ends. Unmarried couples in particular may want a short written agreement about shared purchases.
Decide Which Costs Count as Shared
The split only feels fair if you agree on the list first. Disputes usually come from the gray areas.
| Usually shared | Often personal | Talk about it |
|---|---|---|
| Rent or mortgage | Clothes | Gifts for each other’s families |
| Utilities | Hobbies | Pet costs |
| Groceries | Personal subscriptions | Eating out together |
| Home insurance | Student loans from before the relationship | Childcare |
| Shared car costs | Gym membership | Holidays |
Our tip: Debts from before the relationship are usually personal. Paying them faster still helps the household, though, because it frees up cash sooner. If one of you carries card debt, our debt snowball vs debt avalanche calculations show how to clear it quickly.
Set Up the Accounts for Your Split
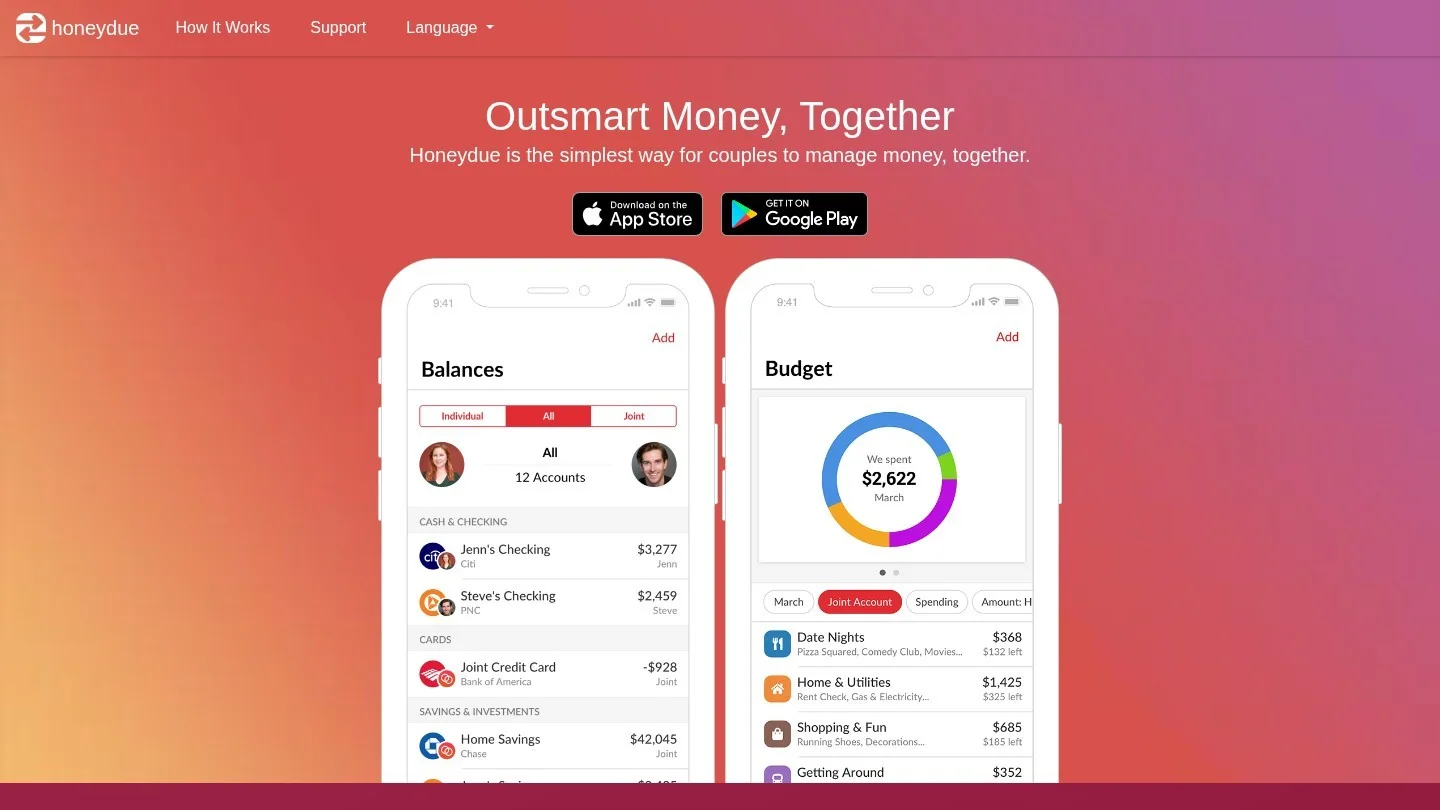
Most couples who split proportionally use three accounts.
- A joint checking account for shared bills. Each partner sends their share on payday by automatic transfer.
- Two personal accounts for individual spending, with no reporting to the other partner.
- A joint savings account for shared goals like trips, a home deposit or an emergency fund.
Then automate the bills from the joint account. Once it runs on autopilot, money talks become a monthly check-in, not a daily argument.
Review the Split When Life Changes
Recalculate the percentages when:
- Either income changes by more than about 10%.
- One partner goes back to school, starts a business or stops working.
- A baby arrives or childcare costs start.
- You move, buy a home or take on a big shared loan.
A 15-minute review once or twice a year keeps the numbers fair without constant scorekeeping.
Related reading: retirement savings calculator and wedding budget calculator.
Splitting Household Expenses: Common Questions
What is the fairest way to split bills with unequal incomes?
For most couples, a proportional split based on take-home pay. Both partners spend the same share of income on shared costs. If you want equal personal spending money instead, use the equal leftover method.
Should the higher earner pay all the rent?
Only if both of you agree and it reflects your other shared costs. Paying all the rent can make sense if the lower earner covers groceries and utilities, as long as the totals line up with your chosen split.
How do you split expenses if one partner does not work?
Most couples pool income in this case. The working partner’s pay covers shared bills, and both partners get an equal personal allowance. Unpaid work at home, such as childcare, also has real value.
Do we need a joint account to split expenses?
No, but it helps. Without one, one partner pays a bill and the other repays them, which is easy to forget. A shared account with automatic transfers removes most of that tracking.