

Should you form an LLC or stay a sole proprietor? Choose an LLC if a client claim, an accident or a business debt could reach your home or savings. Stay a sole proprietor if the work is low risk, you are testing an idea, and you want to start this week with no filing. The tax bill is usually the same at the start, so the real choice is about protection and paperwork.
We went through the IRS and SBA rules for both structures side by side and put every difference into one table. Then we ran five common situations through those rules, from a freelance writer to a food truck. So you can find the case closest to yours and see which structure makes sense.
LLC vs Sole Proprietorship Compared on Liability, Tax and Cost
The SBA puts the main difference in one line. A sole proprietor has unlimited personal liability, while LLC owners are generally not personally liable for the business. Everything else follows from that.
| Point | Sole proprietorship | LLC |
|---|---|---|
| Owners | One person | One or more people |
| Personal liability | Unlimited | Owners are generally not personally liable |
| Separate legal entity | No | Yes |
| Setup | None, you start by doing business | File articles of organization with your state |
| State fees | Usually none to exist, though local licenses still apply | Filing fee and possible yearly fees, which vary by state |
| Default federal tax | Profit goes on your Form 1040 with Schedule C | Single owner is taxed like a sole proprietor by default; two or more owners file as a partnership |
| Self-employment tax | Yes, on net earnings | Yes, on net earnings by default |
| Can choose corporate tax | No | Yes, with Form 8832 |
| Raising money | Hard; you cannot sell shares | Easier; you can add members |
| Registered agent | Not needed | Needed in your state |

How a Sole Proprietorship Works
A sole proprietorship is the default. The IRS defines a sole proprietor as someone who owns an unincorporated business by themselves. So if you start selling a service or product alone and file nothing with the state, you are already one.
That simplicity is the main draw. The SBA says a sole proprietorship is easy to form and gives you complete control. You also do not file a separate business tax return. Instead, you report profit or loss on Schedule C with your Form 1040, and you pay self-employment tax on Schedule SE.
However, the business and the owner are the same person in the eyes of the law. The SBA notes that a sole proprietorship does not create a separate business entity. As a result, a business debt or a court judgment can reach your personal bank account, car or home.
Funding is the other weak spot. The SBA points out that you cannot sell stock, and banks are hesitant to lend to sole proprietors. If you want to trade under a name other than your own, you can still register a trade name. Our guide on what a DBA is explains how that works.
How an LLC Works
An LLC is a business you register with your state. You file articles of organization, which the SBA calls a simple document that describes the basics of your LLC. You also need a registered agent in that state before you file.
Once formed, the LLC is its own legal entity. That is where the protection comes from. The SBA says LLCs protect you from personal liability in most instances, so business debts and claims generally stay with the company.
The LLC can also grow with you. It can have one owner or several, and new members can join. Even so, the SBA warns that some states may require you to dissolve and re-form the LLC when membership changes, unless an agreement covers transfers. So write an operating agreement at the start, even if you are the only owner.
How the IRS Taxes Each Structure
Here many owners expect a big difference, yet the starting point is almost the same. The IRS treats a single-member LLC as an entity disregarded as separate from its owner. In practice, that means you report the LLC’s profit on your own return, much like a sole proprietor.
An LLC with two or more members is a partnership for federal income tax by default. Also, an LLC can choose to be taxed as a corporation by filing Form 8832. The IRS says that choice cannot take effect more than 75 days before the form is filed, or more than 12 months after it.
Single-member LLCs have one wrinkle. For employment tax and some excise taxes, the IRS still treats the LLC as a separate entity. So if your one-owner LLC hires staff, the payroll filings sit with the LLC.
Self-Employment Tax Applies to Both
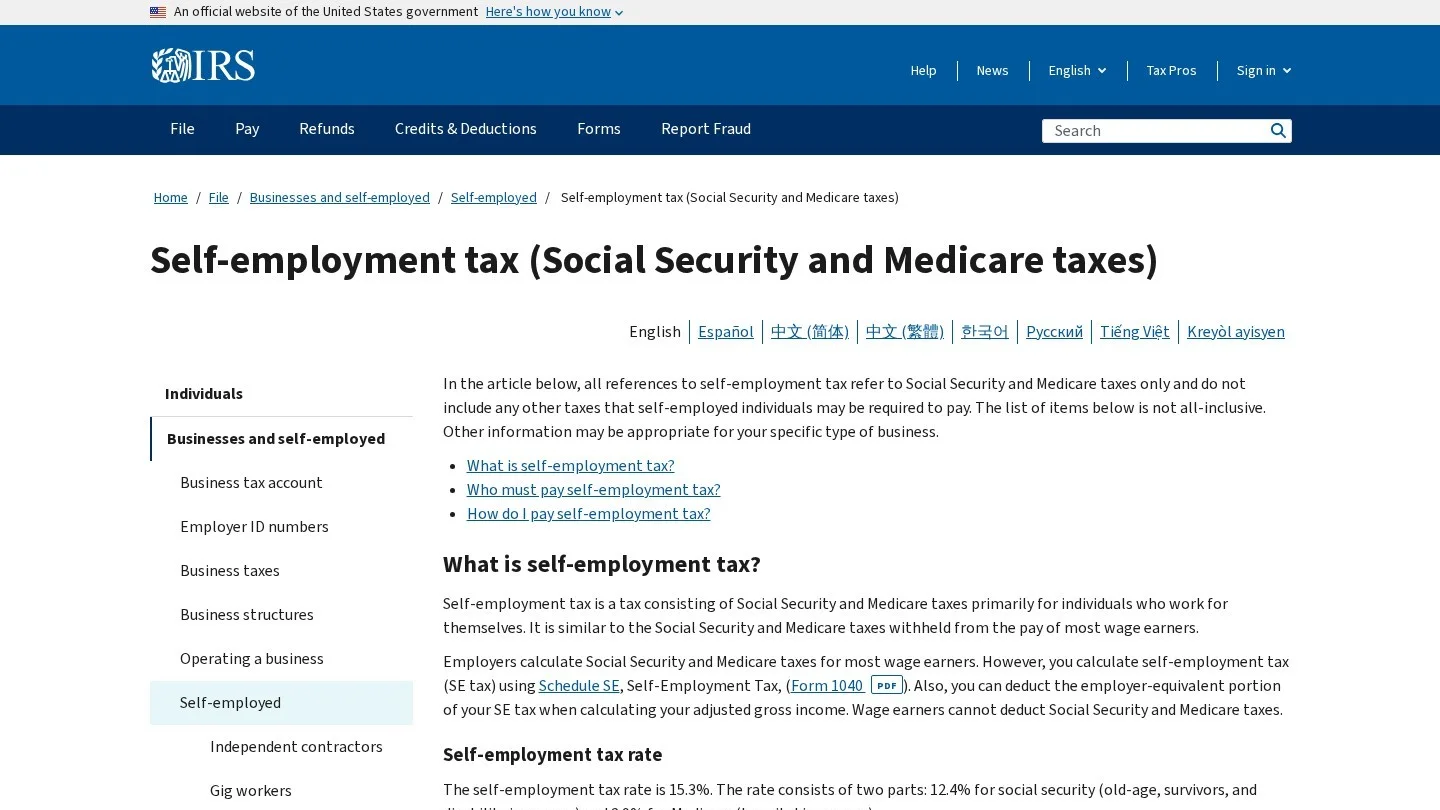
Neither structure escapes self-employment tax by default. The IRS sets the self-employment tax rate at 15.3%. That breaks down into 12.4% for Social Security and 2.9% for Medicare. You owe it once your net earnings reach $400 or more.
The Social Security part has a cap. For 2026, it applies to the first $184,500 of combined wages, tips and net earnings. Above set income levels, an additional 0.9% Medicare tax applies, starting at $200,000 for single filers. You can also deduct the employer-equivalent portion of the tax when you work out your adjusted gross income.
What Each Structure Costs to Set Up and Keep
A sole proprietorship costs nothing to create. You may still need a local business license, a sales tax permit or a trade name filing. Those depend on your city, county and state, and they apply to an LLC too.
An LLC adds a state filing fee. The SBA says the total cost to register a business is usually less than $300, and fees vary by state and structure. Your state may also charge a yearly report fee or tax to keep the LLC active. So check your secretary of state’s website for the exact amounts before you decide.
Then add the ongoing work. An LLC owner should keep a separate bank account, sign contracts in the LLC’s name and file any yearly reports on time. Mixing personal and business money can weaken the liability shield. A simple bookkeeping tool helps, and our list of accounting software for sole traders covers options for one-person firms.
Five Situations and the Structure We Would Pick
The rules make more sense with real cases. So we ran five common business types through them. In each case, risk to your personal assets drives the answer more than tax.
1. A freelance writer testing the market
Risk is low, income is uncertain, and there are no staff or premises. Sole proprietorship. Start under your own name, keep a separate bank account and revisit the choice once income is steady.
2. A handyman or home repair service
Work happens in other people’s homes, and a damaged pipe or an injury can lead to a claim. LLC, plus general liability insurance. The LLC protects personal assets from business debts, while insurance pays claims.
3. Two friends starting an online store
There are two owners, so a sole proprietorship is not an option, because it covers one person only. LLC with an operating agreement that sets out shares, roles and what happens if one person leaves.
4. A food truck with a loan and an employee
The owner has borrowed money, a vehicle, food safety risk and staff. LLC. The IRS also treats even a single-member LLC as a separate entity for employment tax, which keeps payroll filings in the business’s name.
5. A consultant earning well into six figures
Liability may be modest, but taxes now matter more. LLC, then talk to a tax adviser about a corporate tax election with Form 8832. That choice changes how you pay yourself, so the numbers need a professional review.
Switch From Sole Proprietor to LLC
Many owners start as sole proprietors and form an LLC later. The move is simple, and you can make it at any point. Follow these steps:
- Check that your business name is free in your state’s business registry.
- Choose a registered agent, which can be you if your state allows it.
- File articles of organization with the state and pay the filing fee.
- Write an operating agreement, even for a one-owner LLC.
- Get an Employer Identification Number from the IRS if your LLC needs one.
- Open a new business bank account in the LLC’s name.
- Move contracts, licenses, permits and insurance policies to the LLC.
- Update invoices, your website and your business email with the new legal name.
For the wider set of filings a new company faces, our startup compliance checklist for founders lists the common ones. If you are weighing a partnership structure instead, see how to register an LLP in the USA.
When a Sole Proprietorship Still Makes Sense
An LLC is not always worth the cost and paperwork. A sole proprietorship can be the better choice in a few cases:
- You are testing an idea. You can stop at any time without closing a company.
- The work carries little risk. Think tutoring, writing or design work done remotely.
- Insurance already covers the main risks. A good policy handles many claims either way.
- Your state’s fees are high compared with your income. Yearly LLC fees can eat into a small side business.
Even so, revisit the choice each year. Once you sign a lease, hire someone, take on debt or bring in a partner, the case for an LLC gets much better.
LLC and Sole Proprietor Questions Owners Ask
Does an LLC save on taxes compared with a sole proprietorship?
Not by default. A single-member LLC is disregarded for federal income tax, so you report profit the same way and pay the same 15.3% self-employment tax. Savings only come from electing a different tax status.
Can a sole proprietor be sued personally?
Yes. The SBA lists unlimited personal liability for sole proprietors, so business claims and debts can reach personal assets.
How much does it cost to form an LLC?
It depends on your state. The SBA says registering a business usually costs less than $300 in total, and fees vary by state and structure.
Can I have employees as a sole proprietor?
Yes. A sole proprietor can hire staff, but you take on payroll duties and remain personally liable for the business.
Does an LLC protect me from everything?
No. The SBA says LLCs protect owners in most instances. You can still be liable for your own mistakes, and mixing personal and business money can weaken the protection.