A credit card annual fee is worth paying only when the extra rewards and credits you actually use are bigger than the fee. That sounds obvious, but most people never run the numbers. In our test of three real cards on the same $30,000 of yearly spending, the free 2% card beat a $95 travel card and a $795 premium card. The fee cards only came out ahead once the spending pattern or the way points were used changed.
So the credit card annual fee vs rewards question has no single answer. It depends on where your money goes each month and whether you use the perks. This guide gives you a simple formula, then walks through a full comparison you can copy with your own numbers.
The Break-Even Formula
To compare a fee card with a no-fee card, work out the yearly value of each one:
Net value = rewards earned + credits you actually use − annual fee
Then compare the two net values. The fee card is worth it only when its net value is higher.
Three points decide the result:
- Where you spend. Fee cards pay extra in categories such as dining, travel or gas. If most of your spending sits in “everything else”, a flat-rate card often wins.
- What a point is worth to you. A point redeemed for cash back is usually worth 1 cent. Some people get more by transferring points to airlines or hotels, but that takes effort and flexibility.
- Whether you use the credits. A $300 travel credit is worth $300 only if you would have spent that money anyway.
The Three Cards We Compared
We picked three widely used US cards with clear, published terms: one with no annual fee, one with a moderate fee and one premium card.
| Card | Annual fee | Earning rates | Main credit |
|---|---|---|---|
| Citi Double Cash | $0 | 2% cash back on purchases: 1% when you buy, 1% as you pay | None |
| Chase Sapphire Preferred | $95 | 5x on Chase Travel; 3x on dining, gas and EV charging, top streaming services and online grocery; 2x other travel; 1x everything else | Up to $100 a year for hotels booked through Chase Travel |
| Chase Sapphire Reserve | $795 | 8x on Chase Travel; 4x on flights and hotels booked direct; 3x on dining; 1x everything else | Up to $300 a year in travel credits |
The terms come from the issuers’ own pages for the Citi Double Cash, Sapphire Preferred and Sapphire Reserve. Check them again before you apply, because issuers change rates and credits often.
Our Test: $30,000 of Yearly Spending
Next, we built a sample household that spends $30,000 a year on its card:
| Spending type | Yearly amount |
|---|---|
| Dining | $4,000 |
| Gas | $2,000 |
| Online grocery | $2,000 |
| Streaming | $500 |
| Flights and hotels booked direct | $3,000 |
| Everything else | $18,500 |
| Total | $30,000 |
We valued every point at 1 cent, which is what you typically get when you redeem points as cash back. We also assumed the household uses each card’s main credit in full. The spending is a sample, so swap in your own figures.
Citi Double Cash: $30,000 × 2% = $600 a year, with no fee.
Chase Sapphire Preferred:
- 3x on dining, gas, online grocery and streaming: $8,500 × 3 = 25,500 points
- 2x on other travel (the direct flights and hotels): $3,000 × 2 = 6,000 points
- 1x on everything else: $18,500 × 1 = 18,500 points
- Total: 50,000 points = $500
- Plus the $100 hotel credit, minus the $95 fee: $505 a year
Chase Sapphire Reserve:
- 3x on dining: $4,000 × 3 = 12,000 points
- 4x on flights and hotels booked direct: $3,000 × 4 = 12,000 points
- 1x on everything else: $23,000 × 1 = 23,000 points
- Total: 47,000 points = $470
- Plus the $300 travel credit, minus the $795 fee: −$25 a year
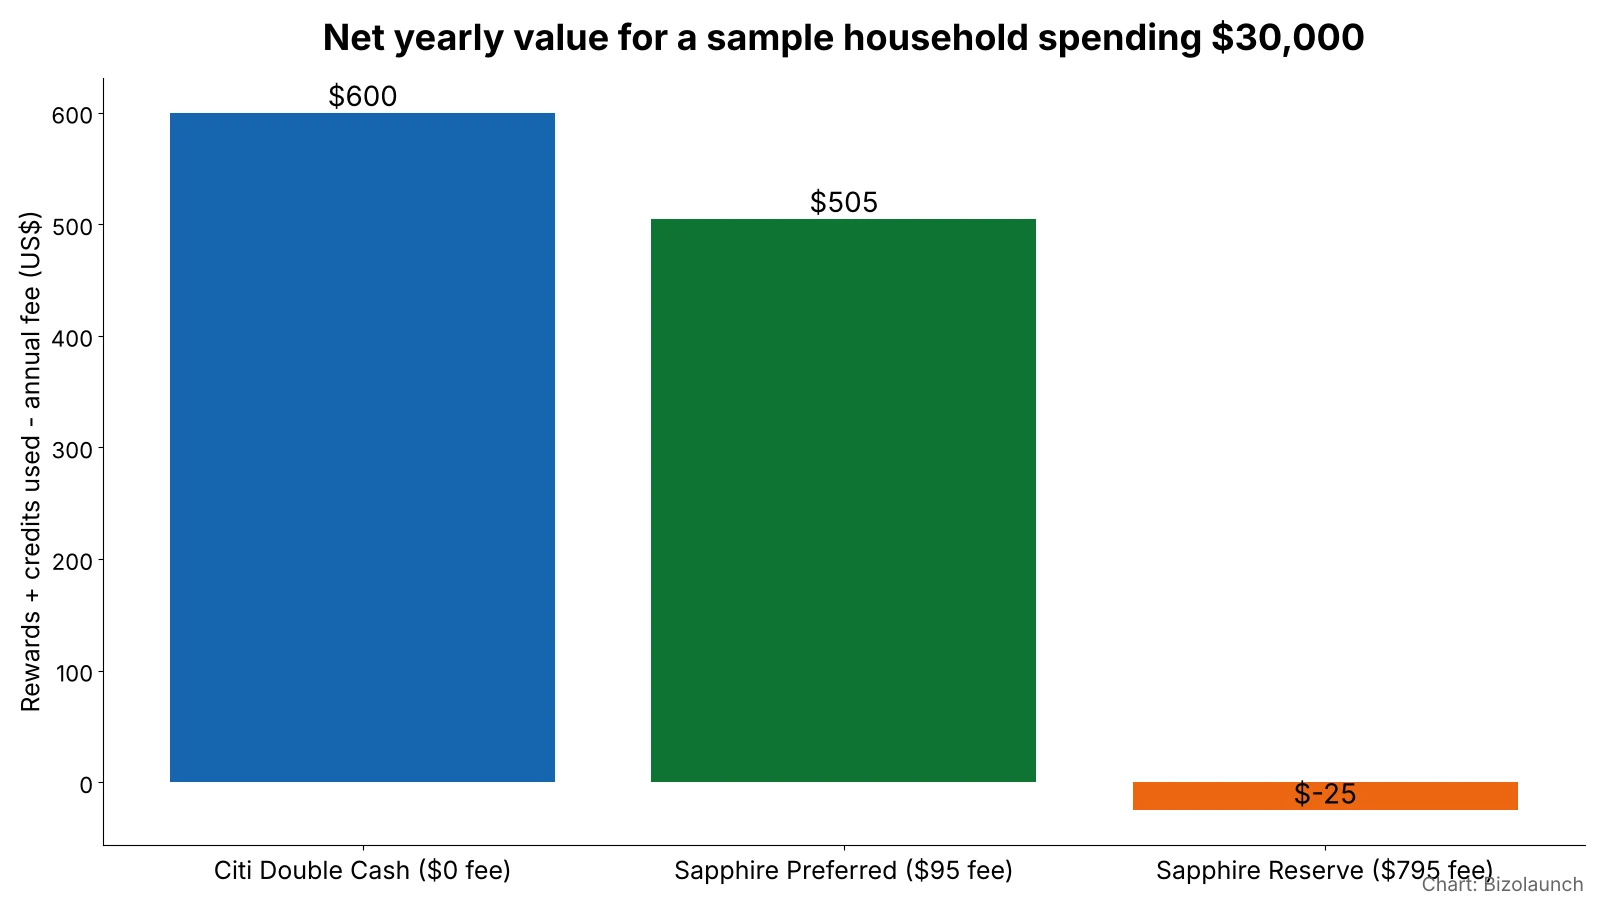
For this household, the no-fee card wins by $95 over the Preferred card and by $625 over the Reserve. In fact, the Reserve costs more than it pays back, even with its full travel credit used.
When the Fee Card Wins Instead
The result flips quickly when the inputs change. Here are the three most common reasons.
1. More spending in bonus categories. Compare the Preferred card with the Double Cash card. Each dollar in a 3x category earns 1 cent more on the Preferred card. Each dollar in “everything else” earns 1 cent less. So, ignoring the hotel credit, the Preferred card only pays for its $95 fee once your 3x spending is at least $9,500 more than your 1x spending. Add the $100 hotel credit, and the gap almost disappears.
2. Higher value per point. If you transfer points to airline or hotel partners and get, say, 1.25 cents per point, the Preferred card’s 50,000 points become $625. Its net value rises to $630, which beats the Double Cash card’s $600. That only works if you are flexible with dates and willing to learn how award bookings work.
3. The welcome bonus in year one. The Sapphire Preferred offers 75,000 points after you spend $5,000 in the first 3 months. At 1 cent a point, that is $750 on top of the first year’s rewards. So almost any fee card wins in its first year. The real question is whether it still wins in year two, when the bonus is gone and the fee renews.
Signs an Annual Fee Card Is Worth It for You
A fee card usually makes sense when most of these are true:
- You spend heavily in the card’s bonus categories, such as dining or travel.
- You would use the card’s credits even if the card didn’t offer them.
- You redeem points for travel at more than 1 cent each.
- You pay your balance in full every month.
- You value perks the numbers miss, such as airport lounge access or travel insurance.
Signs You Should Stick With a No-Fee Card
On the other hand, a no-fee card is the better choice when:
- Most of your spending falls outside bonus categories.
- You prefer simple cash back over managing points.
- You sometimes carry a balance. Interest of 19% or more quickly wipes out any reward. For example, the Sapphire Preferred’s variable APR is 19.49% to 27.74%.
- You would “use” a credit only by spending money you otherwise wouldn’t.
That last point catches many people. A $300 travel credit is not $300 of value if it pushes you to book a trip you didn’t need.
Should You Downgrade or Cancel a Fee Card?
If your numbers show the fee isn’t paying off, you have options before you cancel:
- Ask for a product change to a no-fee card from the same issuer. You keep the account history, which helps your credit score.
- Ask about a retention offer when the fee posts. Issuers sometimes offer bonus points or a statement credit to keep you.
- Use your points first. Redeem the points before you close or change the card, so you don’t lose them.
Then run the formula again each year when the fee renews. Your spending changes, and so do the cards.
How to Run the Numbers for Your Own Card
- Download the last 12 months of card statements.
- Sort your spending into the card’s bonus categories and “everything else”.
- Multiply each group by its earning rate.
- Value the points at the rate you actually redeem them, usually 1 cent.
- Add only the credits you would use anyway.
- Subtract the annual fee.
- Repeat for a no-fee card and compare.
It takes about 30 minutes, and it may save you hundreds of dollars a year. If you want to know how much your points are really worth before you redeem them, read our guide to credit card reward points value.
This guide explains how to compare cards. It is not personal financial advice, so check each card’s current terms and your own situation before you apply.