A doctor earning $300,000 a year can have a lower net worth than a teacher earning $60,000. How? Income is the money that comes in over a period, such as a salary for one year. Net worth is a snapshot: everything you own minus everything you owe, on a single day. One measures flow. The other measures what is left over.
We took the Federal Reserve’s household survey and worked out how net worth compares with income at each age. That gave us a simple ratio you can check yourself against. The examples in this guide use round sample numbers so the math is easy to follow.
What Income Means
Income is money you receive over a set period. Most people think of a yearly salary. However, income also covers wages from a side job, business profit, rent from a tenant, interest, dividends and benefits.
There are two numbers to know. Gross income is what you earn before taxes and deductions. Net income, or take-home pay, is what lands in your bank account. For example, a $70,000 salary might leave far less after tax, retirement savings and health insurance.
The Federal Reserve counts family income before tax, for the full year before its survey. So when you compare yourself with Fed data, use your gross income.
Income tells you how much you can spend or save each month. Still, it says nothing about what you have kept from past years.
What Net Worth Means
Net worth is the value of what you own minus what you owe. Colorado State University Extension puts it this way: “Your net worth is the difference between your assets (what you own) minus your debts (what you owe).”
Assets include cash, savings, retirement accounts, investments, the market value of your home and car, and any business you own. Debts include your mortgage, car loan, student loans, credit card balances and unpaid bills.
The formula is short:
Net worth = total assets − total debts
Value assets at what you could sell them for today. The same Extension guide says to use market value, “not what it cost when it was new.” So a car bought for $35,000 might count as $22,000 on your statement.
Net worth can be negative. That happens when debts are larger than assets. For example, a new graduate with large student loans and little savings can begin adult life with a negative number.
Net Worth vs Income Compared
The two numbers answer different questions. This table puts them side by side.
| Point | Income | Net worth |
|---|---|---|
| What it measures | Money coming in | Wealth left after debts |
| Time frame | A period, such as a month or a year | One point in time |
| Formula | Wages + other earnings | Assets − debts |
| Can it be negative? | Rarely | Yes, if debts exceed assets |
| Where you see it | Payslip, tax return | A net worth statement you build |
| What raises it | A raise, a side job, a business | Saving, paying down debt, rising asset values |
| What it tells you | What you can afford now | How secure you are over time |
In accounting terms, income looks like a profit and loss statement for your household. Net worth looks like a balance sheet. If you run a business, our guide on reading a profit and loss statement shows the same split.
Worked Example 1: High Income, Low Net Worth
Meet Alex, a sample earner. Alex makes $180,000 a year. On paper, Alex is doing well. Then look at the balance sheet.
| Alex’s assets | Value | Alex’s debts | Value |
|---|---|---|---|
| Checking and savings | $8,000 | Mortgage | $520,000 |
| Retirement account | $40,000 | Car loan | $45,000 |
| Home (market value) | $560,000 | Credit cards | $18,000 |
| Car (market value) | $38,000 | Student loans | $60,000 |
| Total assets | $646,000 | Total debts | $643,000 |
Alex’s net worth is $646,000 − $643,000 = $3,000. That is less than one week of Alex’s pay. So a high income does not build wealth on its own. Large loans and spending can absorb almost all of it.
Worked Example 2: Modest Income, Higher Net Worth
Now meet Sam, another sample earner. Sam makes $62,000 a year and has done so for 20 years.
| Sam’s assets | Value | Sam’s debts | Value |
|---|---|---|---|
| Savings | $25,000 | Mortgage | $90,000 |
| Retirement accounts | $210,000 | Car loan | $0 |
| Home (market value) | $320,000 | Credit cards | $0 |
| Car (market value) | $9,000 | Other loans | $0 |
| Total assets | $564,000 | Total debts | $90,000 |
Sam’s net worth is $564,000 − $90,000 = $474,000. That is more than seven times Sam’s yearly income. Sam kept debts low, drove an older car and saved steadily. Time did the rest.
The lesson from both examples is the same. Income is the raw material. Net worth is what you build with it.
How Net Worth and Income Change With Age
The Federal Reserve’s Survey of Consumer Finances tracks both numbers for US families. Its latest published survey report covers 2022. All figures are in 2022 dollars.
| Age of family head | Median income | Median net worth |
|---|---|---|
| Under 35 | $60,500 | $39,000 |
| 35 to 44 | $85,900 | $135,600 |
| 45 to 54 | $91,900 | $247,200 |
| 55 to 64 | $81,900 | $364,500 |
| 65 to 74 | $60,900 | $409,900 |
| 75 and over | $49,100 | $335,600 |
| All families | $70,300 | $192,900 |
Median income peaks between 45 and 54. However, median net worth keeps rising until 65 to 74. That gap is the whole story of saving. People keep building wealth for years after their pay stops growing, and then they draw it down in retirement.
Our Net Worth to Income Ratio by Age
Next, we divided median net worth by median income for each age group. This ratio tells you how many years of income the typical family has saved up in wealth.
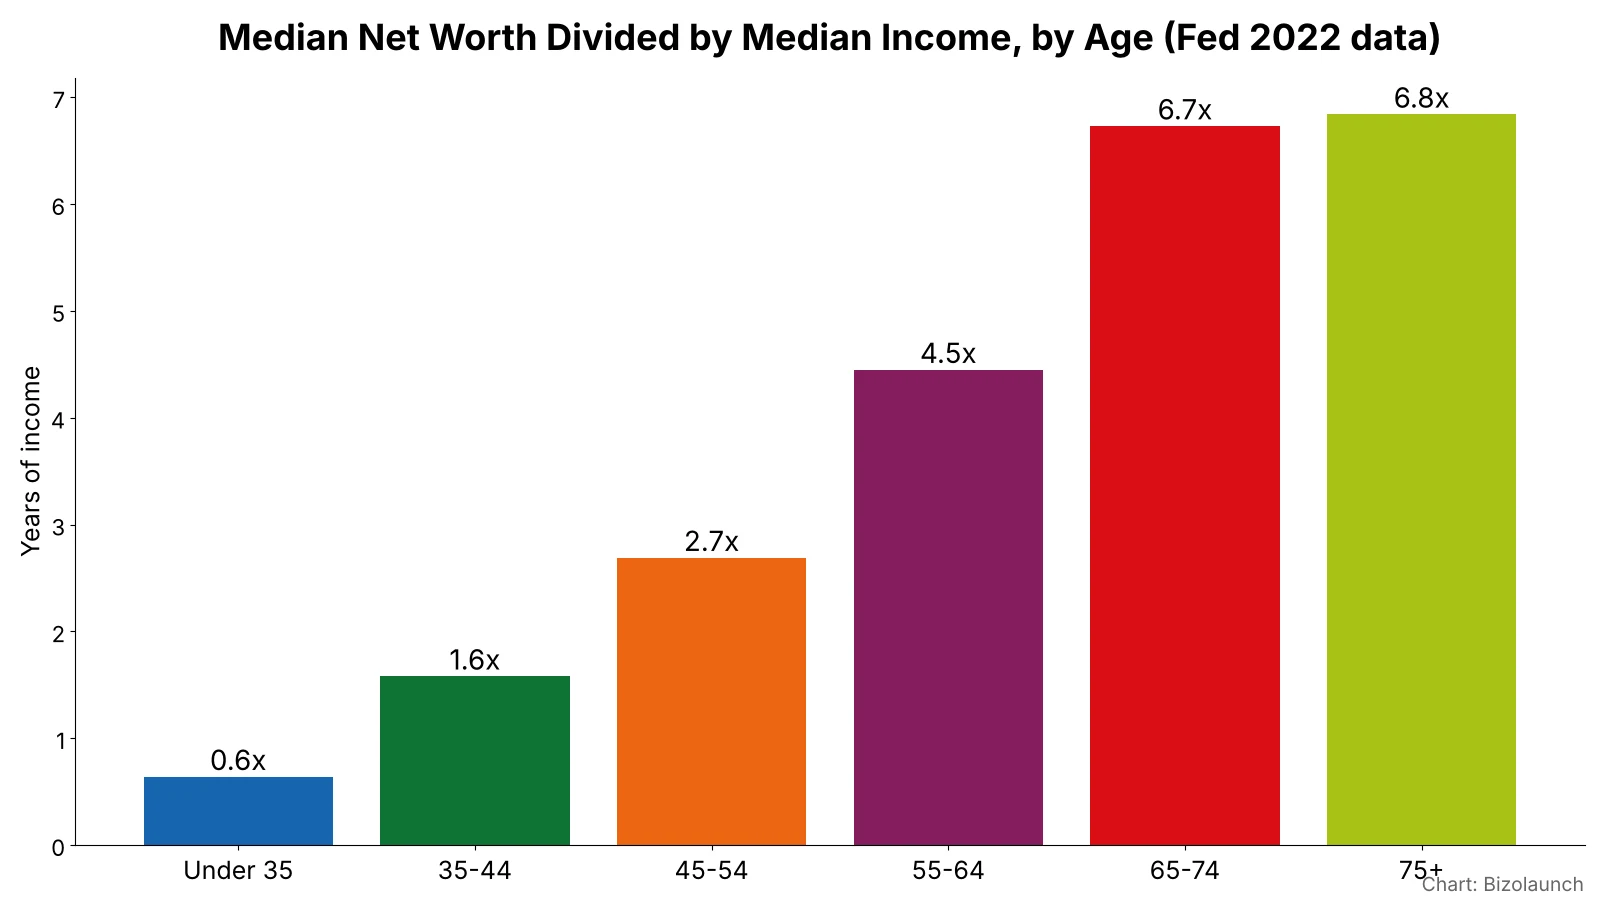
The typical family under 35 holds wealth worth about 0.6 years of income. By 45 to 54, that rises to about 2.7 years. Then, by 65 to 74, it reaches about 6.7 years.
You can run the same check on yourself. Divide your net worth by your gross yearly income. Then compare the result with your age group. For example, a 40-year-old with a net worth of $200,000 and income of $100,000 has a ratio of 2.0. That sits above the 1.6 median for ages 35 to 44.
Keep in mind these are medians, not targets. Your ratio depends on where you live, your home equity and how long you have worked.
A Rule of Thumb for Net Worth From Income
Colorado State University Extension mentions one rule from the book The Millionaire Next Door. Your target net worth equals your age times your gross yearly income, divided by 10.
For example, a 40-year-old earning $90,000 would aim for 40 × $90,000 ÷ 10 = $360,000. Compare that with the Fed’s $135,600 median for families aged 35 to 44. So the rule sets a high bar. Use it as a stretch goal, not a pass or fail test.
Mean vs Median: Why Averages Mislead
You may see much bigger “average” figures online. The Fed’s 2022 mean net worth for all families was $1,063,700. Yet the median was only $192,900.
The mean adds everyone up and divides by the number of families. So a small group of very rich households pulls it up. The median is the middle family. For that reason, the median is the better number to compare yourself with.
Income shows the same pattern, though less extreme. The 2022 mean family income was $141,900, while the median was $70,300.
How to Grow Net Worth on Any Income
Net worth grows in only two ways. Assets go up, or debts go down. So focus on the gap between what you earn and what you spend.
- Build a net worth statement. List every asset at today’s value and every debt. Colorado State Extension suggests doing this once a year, at about the same time, and comparing the two statements.
- Pay down high-interest debt. Every dollar of credit card debt you pay off raises net worth by a dollar. Our guide to debt snowball vs debt avalanche helps you pick an order.
- Save part of every raise. When income goes up, move some of the increase to savings before you adjust your spending.
- Invest for the long term. Retirement accounts grow over decades. Our retirement savings calculator shows what steady saving can add up to.
- Think about big purchases. A larger home or a new car can cut net worth when the loan is bigger than the value. Our rent vs buy guide runs the numbers.
Tracking spending makes all of this easier. If your household has two earners, our guide on budgeting with two sources of income shows one way to split it.
Net Worth vs Income Questions
Is net worth the same as income?
No. Income is what you earn over a period, such as a year. Net worth is what you own minus what you owe, measured on one day.
Does net worth include income?
Not directly. Income only adds to net worth once you save it or use it to pay down debt. Money you spend does not raise net worth.
Can you have a high income and a negative net worth?
Yes. If your debts are larger than your assets, your net worth is negative, no matter how much you earn. A new graduate with large student loans is one example.
Does net worth include your house?
Yes. Count your home at its current market value as an asset. Then count the mortgage as a debt. The difference is your home equity.
What is the median net worth in the US?
The Federal Reserve’s 2022 survey put median family net worth at $192,900. Median family income in the same survey was $70,300.